Executive Summary & Key Takeaways
Dealing with collection accounts on your credit report can feel like fighting an uphill battle against a faceless institution. However, the Fair Credit Reporting Act (FCRA) provides a powerful federal framework designed to protect consumers from inaccurate data reporting. The cornerstone of this protection is FCRA Section 611.
- Legal Right to Dispute: FCRA Section 611 grants consumers the federal right to dispute inaccurate, incomplete, or unverifiable information on their credit reports.
- 30-Day Investigation Window: Credit bureaus legally have 30 days to investigate and respond to your factual dispute.
- Potential Deletion: If the data furnisher cannot verify the accuracy of the collection account within the statutory timeframe, the item may be eligible for deletion as unverified. This is a self-help, DIY educational process.
- Paper Trails Matter: Always dispute in writing using USPS Certified Mail to establish a legally binding timeline.
1. Understanding FCRA Section 611 (15 U.S.C. § 1681i)
Section 611 of the FCRA outlines the procedure in case of disputed accuracy. In plain English, if a consumer notifies a consumer reporting agency (Equifax, Experian, or TransUnion) that an item on their file is inaccurate or incomplete, the agency is required to conduct a reasonable investigation free of charge within 30 days under federal law. This is a self-help, DIY educational process.
This is not a loophole—it is a strict federal compliance standard. The burden of proof is not on you to prove the account is false. The burden of proof is on the credit bureau and the data furnisher (the collection agency) to prove that the data is 100% accurate, complete, and verifiable according to Metro 2 reporting standards.
2. The Metro 2 Compliance Standard in Collections Reporting
Credit bureaus use an automated system called e-OSCAR to process disputes. Data is formatted using the Metro 2 standard. If a collection agency reports an account, every single data field—from the Date of First Delinquency (DOFD) to the Account Status Code—should be perfectly aligned. If you identify a reporting inaccuracy or field contradiction across Equifax, Experian, or TransUnion, the account may be non-compliant and may be eligible for correction or deletion under 15 U.S.C. § 1681i(a)(5)(A). This is a self-help, DIY educational process to verify data format compliance.
               ┌────────────────────────────────────────────────┐
               │    METRO 2 DATA FIELD COMPLIANCE AUDIT         │
               └───────────────────────┬────────────────────────┘
                                       │
     ┌─────────────────────────────────┼─────────────────────────────────┐
     ▼                                 ▼                                 ▼
┌───────────────────────┐   ┌───────────────────────┐   ┌───────────────────────┐
│ Date of First         │   │ Current Balance vs.   │   │ Account Status Code   │
│ Delinquency (DOFD)    │   │ Original Charge-Off   │   │ vs. Payment History   │
└────────────┬──────────┘   └───────────┬───────────┘   └───────────┬───────────┘
             │                          │                           │
             └──────────────────────────┼───────────────────────────┘
                                        │
                                        ▼
                   [ Contradiction Found = Non-Compliant Data ]
                                        │
                                        ▼
                 [ Mandatory Modification or Immediate Deletion ]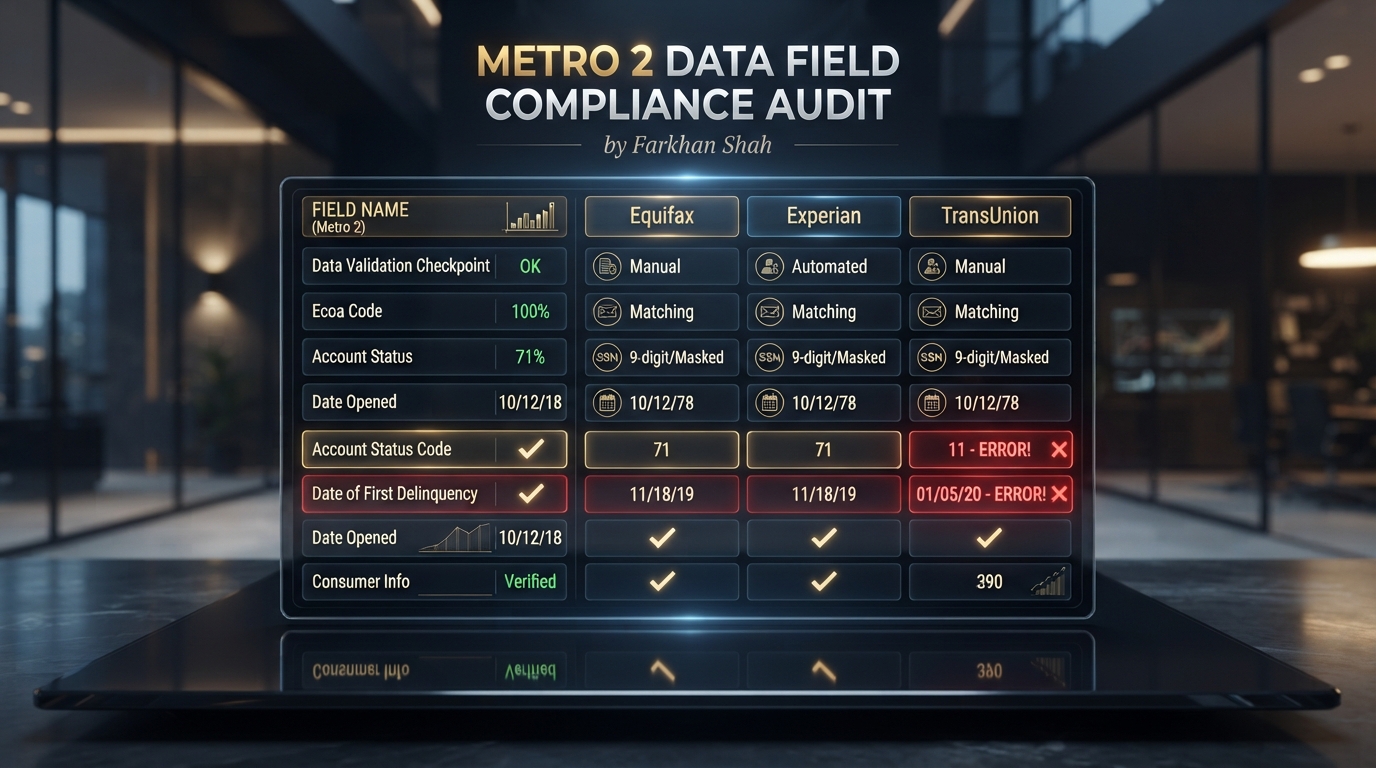
Don't let credit bureaus dismiss your disputes with generic form letters. Download our educational dispute workflows and 21+ copy & paste templates to help you exercise your FCRA rights and identify reporting inaccuracies.
3. Step-by-Step Action Plan: Executing a Section 611 Dispute
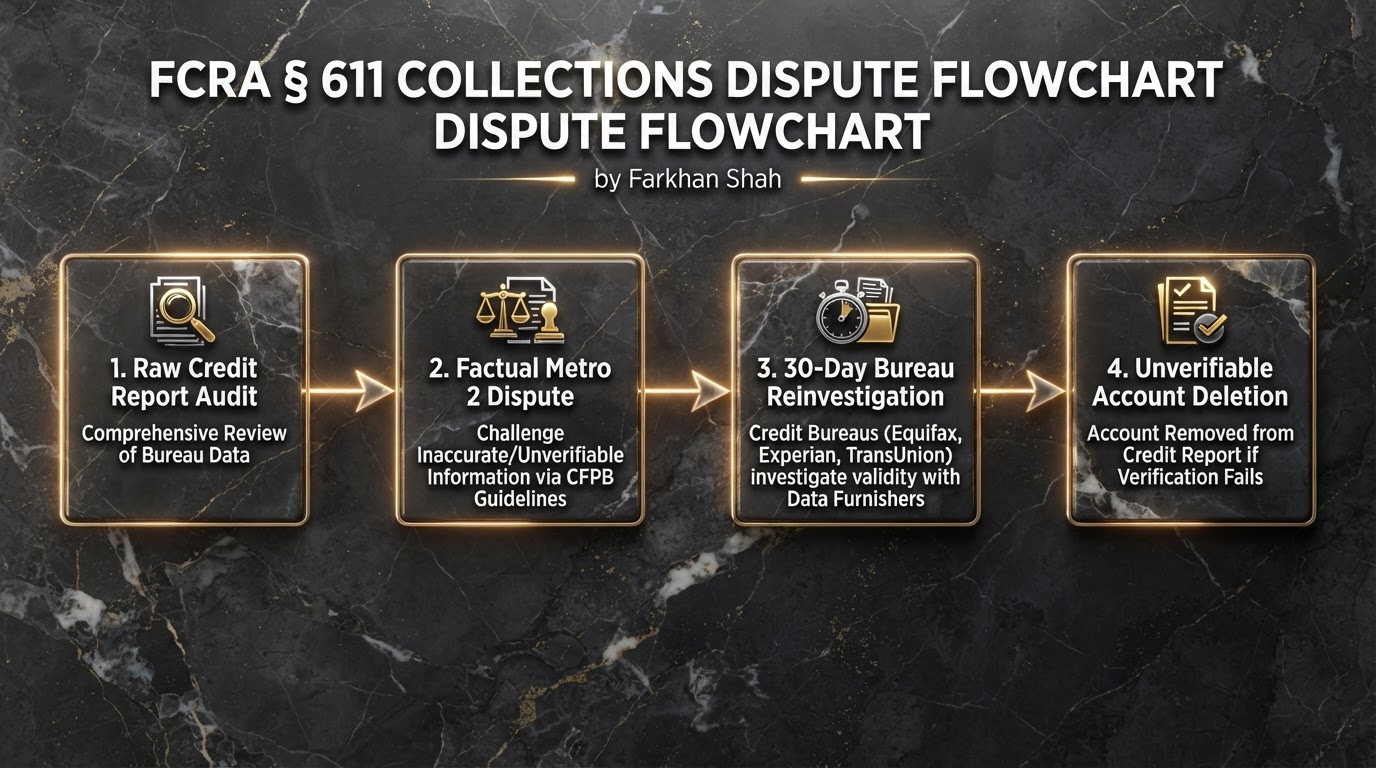
To leverage Section 611 effectively, approach your dispute logically and systematically as a self-help, DIY educational process. Do not use generic online templates that claim an account is "not yours." Follow this factual process to identify reporting inaccuracies and exercise your FCRA rights:
- Obtain Your Raw Data: Pull your official credit reports directly from AnnualCreditReport.com. Do not rely on third-party monitoring apps, as they summarize or hide critical Metro 2 data fields.
- Identify the Inaccuracies: Cross-reference the collection account across all three bureaus. Look for discrepancies in the Date Opened, Balance, Date of Last Activity, and Account Status.
- Draft a Factual Dispute: Write a letter directly to the credit bureaus pointing out the specific data field that is inaccurate. State clearly that you are requesting a formal reinvestigation under FCRA Section 611.
- Send via Certified Mail: Online portals may require you to accept terms that can limit your documentation trail. To exercise your FCRA rights effectively, send your physical letter via USPS Certified Mail with Return Receipt Requested to establish a clear "Day 1" timeline.
- Review the Reinvestigation Results: After 30 days, the bureau should provide you with written results. If the collection agency failed to verify the mismatched data, the record may be eligible for deletion as unverified under 15 U.S.C. § 1681i(a)(5)(A).
4. Interactive Tools & Video Breakdown
Use our free interactive generator directly on this page to pre-fill your Section 611 dispute letter, copy the exact statutory text, or export a formatted file instantly.
FCRA Section 611 Dispute Letter & Instant PDF Generator
Customize your factual Metro 2® collection dispute letter, preview in real time, and export directly to a formal 1-page printable PDF or certified mail document.
Bureau & Collection Account Details
Consumer Identity & Factual Discrepancy
Jane R. Doe
456 Factual Dispute Blvd, Suite 200
Atlanta, GA 30301
SSN (Last 4): XXX-XX-4321 | DOB: 04/22/1988

DATE: August 26, 2026
DELIVERY METHOD: USPS CERTIFIED MAIL w/ RETURN RECEIPT REQUESTED

TO:
Equifax Information Services LLC
P.O. Box 740256
Atlanta, GA 30374

RE: STATUTORY FORMAL NOTICE OF FACTUAL DATA DISPUTE & MANDATORY REINVESTIGATION PURSUANT TO 15 U.S.C. § 1681i(a) (FCRA § 611)

Disputed Entity / Collection Agency: Midland Credit Management
Account / Reference Number: 4829-XXXX-8910

Dear Consumer Dispute Compliance Department,

I am writing to issue a formal, statutory notice of factual dispute pursuant to Section 611 of the Fair Credit Reporting Act (15 U.S.C. § 1681i). I have audited my official credit report and identified specific, material inaccuracies in the Metro 2® electronic reporting data maintained by your agency for the account referenced above.

1. STATUTORY DUTY TO REINVESTIGATE (15 U.S.C. § 1681i(a)(1))
Under federal law (15 U.S.C. § 1681i(a)(1)(A)), upon receipt of this dispute notice, your agency is legally obligated to conduct a free, reasonable, and complete reinvestigation within thirty (30) calendar days to determine whether the disputed information is inaccurate, incomplete, or unverifiable.

2. SPECIFIC FACTUAL AND METRO 2® REPORTING INACCURACY:
I am disputing the account for the following specific factual data defects:
The reported collection balance of $2,450 on Equifax contradicts the $0 balance reported on Experian and the original $1,800 charge-off amount, violating Metro 2® Base Segment Field 21 accuracy rules under FCRA § 623.

3. EXCLUSION OF AUTOMATED "FRIVOLOUS" CLASSIFICATION:
This communication is a factual, data-specific statutory dispute. It is NOT a generic internet template. Any attempt by your automated e-OSCAR OCR scanner to label this notice as "frivolous or irrelevant" under 15 U.S.C. § 1681i(a)(3) without conducting a physical human audit with the furnisher constitutes willful non-compliance under 15 U.S.C. § 1681n.

4. MANDATORY STATUTORY DELETION (15 U.S.C. § 1681i(a)(5)(A))
If the data furnisher (Midland Credit Management) fails to verify the absolute accuracy of every disputed field with original source documentation within thirty (30) calendar days of receipt, 15 U.S.C. § 1681i(a)(5)(A) mandates that your agency MUST PROMPTLY DELETE THAT ITEM from my credit file.

ENCLOSURES ATTACHED FOR IDENTITY VERIFICATION:
- Copy of Valid Government Photo Identification
- Copy of Proof of Address (Utility Bill / Bank Statement)

Please forward written notification of the reinvestigation results and an updated copy of my credit report reflecting the deletion or correction of this item to my address above within 30 days.

Respectfully submitted,

________________________________________
Jane R. Doe
FCRA § 609 / § 611 Legal Requirement Checker
Audit your dispute strategy against federal statutory standards to ensure maximum legal leverage under 15 U.S.C. § 1681g and 15 U.S.C. § 1681i before mailing.
Your current approach lacks statutory force under FCRA § 611. Bureaus will likely respond with a rubber-stamp 'Verified' or 'Frivolous Dispute' template letter.
Formally requested all underlying data, source documents, and furnisher records held in bureau files.
Sent via USPS Certified Mail with signature confirmation establishing day-1 receipt proof.
Dispute cites specific Metro 2 fields (e.g. Account Status vs Payment Rating or DOFD re-aging error).
Includes original factual documentation and avoids generic template quotes that trigger e-OSCAR auto-rejection.
If verified without change, demands business name, address, phone number, and procedure description within 15 days.
Includes statutory language demanding immediate deletion if unverified within the 30-day statutory window.
FCRA § 611 30-Day Investigation Deadline Calculator
Input your USPS Certified Mail delivery confirmation date to calculate the exact statutory investigation deadline and enforce mandatory deletion rights under federal law.
Select the delivery date stamped on your USPS Certified Mail Return Receipt (Green Card).
Each bureau receives a separate Certified Mail delivery trigger.
Sending new supporting info during an active 30-day investigation legally grants the bureau an extra 15 days (extending deadline from 30 to 45 calendar days).
Active Investigation Window (5 Days Remaining)
Enforcement Protocol: Equifax has until Mon, Aug 31, 2026 (5 calendar days remaining) to complete its reinvestigation. If written results with verification details are not postmarked by this date, you have immediate grounds to demand permanent removal under FCRA § 611(a)(5)(A).
NOTICE OF MANDATORY DELETION UNDER 15 U.S.C. § 1681i(a)(5)(A)

TO: EQUIFAX CONSUMER DISPUTE DEPARTMENT
RE: EXPIRATION OF STATUTORY 30-DAY REINVESTIGATION PERIOD
ACCOUNT IN DISPUTE: Midland Credit Management #8492
USPS CERTIFIED MAIL TRACKING #: 7021 0370 0001 8293 4012
DATE OF CONFIRMED DELIVERY: Sat, Aug 1, 2026
STATUTORY DEADLINE EXPIRED: Mon, Aug 31, 2026

Dear Dispute Supervisor,

On Sat, Aug 1, 2026, your agency confirmed receipt of my formal factual dispute regarding the above-referenced account via USPS Certified Mail (Tracking #: 7021 0370 0001 8293 4012).

Under Section 611(a)(1) of the Fair Credit Reporting Act (15 U.S.C. § 1681i(a)(1)), your agency had exactly 30 calendar days to conduct a reasonable reinvestigation and provide written results. As of Wed, Aug 26, 2026, that statutory window has officially expired without certified verification.

PURSUANT TO 15 U.S.C. § 1681i(a)(5)(A):
"If an item of information disputed by a consumer is found to be inaccurate or incomplete or CANNOT BE VERIFIED, the consumer reporting agency shall PROMPTLY DELETE that item of information from the file of the consumer..."

DEMAND FOR ACTION:
Because your agency failed to verify the disputed item within the statutory 30-day timeframe, you are legally mandated to DELETE this unverified tradeline immediately and issue an updated copy of my credit disclosure within 5 business days.

Sincerely,
[Your Legal Name]
[Your Address]
[Your SSN (Last 4) & DOB]
FCRA § 609 / § 611 Method of Verification (MOV) Generator
Generate a legally binding Method of Verification demand letter under 15 U.S.C. § 1681i(a)(7) to force credit bureaus to supply physical furnisher contact details or delete rubber-stamped accounts.
Target Bureau & Disputed Tradeline
Consumer Info & Specific Inaccuracy
Johnathan Doe
123 Financial Freedom Way, Suite 400
Austin, TX 78701
SSN (Last 4): XXX-XX-6789 | DOB: 01/15/1985

DATE: August 26, 2026
VIA USPS CERTIFIED MAIL w/ RETURN RECEIPT

TO:
Equifax Information Services LLC
P.O. Box 740256
Atlanta, GA 30374

RE: FORMAL METHOD OF VERIFICATION (MOV) DEMAND PURSUANT TO 15 U.S.C. § 1681i(a)(7) & 15 U.S.C. § 1681g
Prior Dispute Submission Date: June 12, 2026
USPS Certified Mail Tracking #: 7020 0640 0001 2345 6789
Disputed Account / Furnisher Name: Midland Credit Management
Account Number: 4829-XXXX-8910

Dear Compliance Director,

I am writing to formally exercise my statutory consumer rights under the Fair Credit Reporting Act (FCRA), specifically 15 U.S.C. § 1681i(a)(7) and 15 U.S.C. § 1681g (Section 609).

On June 12, 2026, your agency received my certified written dispute regarding the inaccurate tradeline referenced above. Your agency subsequently returned a response stating that the account was "Verified." However, your notice failed to include the legally mandated description of the procedure used to determine the accuracy of the disputed item.

1. STATUTORY DEMAND FOR METHOD OF VERIFICATION (15 U.S.C. § 1681i(a)(7))
Pursuant to FCRA § 611(a)(7), I hereby demand that your agency provide me, within fifteen (15) calendar days of receipt of this notice:
a) The exact business name, physical street address, and direct telephone number of the specific individual or department at Midland Credit Management contacted during your reinvestigation.
b) A written description of the verification procedure utilized, including whether the verification was conducted electronically via an automated e-OSCAR Automated Dispute Verification (ADV) code or through physical document inspection.
c) Copies of the underlying source documents (signed credit application, payment history ledger, or original contract) provided by Midland Credit Management to substantiate accuracy.

2. SPECIFIC FACTUAL INACCURACY
The item in question remains legally unverifiable and non-compliant due to:
The bureau issued a generic 'Verified' response without supplying the physical source documents, signed contract, or payment history records provided by the furnisher.

3. NOTICE OF MANDATORY DELETION (15 U.S.C. § 1681i(a)(5)(A))
Under 15 U.S.C. § 1681i(a)(5)(A), if disputed information cannot be verified through complete, documented source evidence within the statutory timeframe, your agency is legally required to PROMPTLY DELETE THAT ITEM from my credit file. An automated e-OSCAR "rubber-stamp" code does not satisfy the legal standard of a reasonable investigation under 15 U.S.C. § 1681i(a)(1).

Please send your full Method of Verification disclosure and updated credit report reflecting the immediate deletion of this unverified item to my address above within 15 days.

Sincerely,

________________________________________
Johnathan Doe
FCRA Section 611 Dispute & Enforcement Cheat Sheet
30-Day Reinvestigation Clock, Metro 2 Audit Checkpoints, MOV Escalation Rules, and CFPB Protocol.
Under FCRA § 611(a)(1), bureaus have 30 calendar days from confirmed USPS Certified Mail delivery to complete investigation.
Under 15 U.S.C. § 1681i(a)(5)(A), if an item cannot be verified as 100% accurate within 30 days, it must be deleted immediately.
Sending extra letters during an active 30-day investigation gives bureaus an additional 15 days (extending the clock to 45 days).
| Audit Stage | Statutory Action / Checkpoint | FCRA Legal Citation | Enforcement Trigger |
|---|---|---|---|
| Step 1: Certified Dispute | Send written dispute via USPS Certified Mail with Return Receipt. Attach Photo ID & Utility Bill. | 15 U.S.C. § 1681i(a)(1) | Establishes legal "Day 1" on green card receipt date. |
| Step 2: Metro 2 Field Audit | Check DOFD (Field 25), Account Status Code 97 vs Payment Rating Code 11, and Scheduled Payment ($0 on collections). | 15 U.S.C. § 1681e(b) & § 623 | Data field contradictions prove non-compliant reporting. |
| Step 3: Frivolous Rebuttal | If bureau sends e-OSCAR template rejection, issue notice of specific Metro 2 field errors within 5 days. | 15 U.S.C. § 1681i(a)(3) / § 612 | Forces bureau supervisor to conduct manual reinvestigation. |
| Step 4: MOV Escalation | If item is "Verified" without changes, demand Method of Verification (furnisher contact name, phone, & procedure). | 15 U.S.C. § 1681i(a)(7) | Bureau must respond in 15 days or delete item. |
| Step 5: Regulatory Complaint | File CFPB complaint + FTC & State AG report. Attach Certified Mail proof + Bureau non-compliant response. | CFPB / FTC / State UDAP | Bypasses automated offshore scanners and triggers legal review. |
Author: Chief AI Architect Farkhan Shah, Everything AI, LLC • creditrepair.everythingainow.com
Section 611 Collections Removal Strategy
Watch Chief AI Architect Farkhan Shah demonstrate how to locate Metro 2® field errors and prepare your statutory Section 611 dispute letter.
In this video guide: Learn how to spot Metro 2® data mismatches across Equifax, Experian, and TransUnion and pre-fill your dispute letter.
Choose Your Path to Credit Clarity
Every consumer's credit situation and timeline are unique. We offer two clear ways to resolve inaccurate collection accounts:
       ┌─────────────────────────────────────────────────────────┐
       │               SELECT YOUR CREDIT SOLUTION               │
       └────────────────────────────┬────────────────────────────┘
                                    │
           ┌────────────────────────┴────────────────────────┐
           ▼                                                 ▼
┌───────────────────────────┐                     ┌───────────────────────────┐
│     DIY MASTER SYSTEM     │                     │   1-ON-1 VIP STRATEGY     │
 │           $17             │                     │          $197             │
├───────────────────────────┤                     ├───────────────────────────┤
│ • 35-Page Operational     │                     │ • Includes Full $17 DIY   │
│   Credit Repair Blueprint │                       Blueprint Suite           │
│ • 21+ FCRA & Metro 2      │                     │ • 1-on-1 Personal File    │
│   Dispute Templates       │                       Audit & Strategy Call     │
│ • MOV & Bureau Escalation │                     │ • Step-by-Step Customized │
│   Letter Sequences        │                       Action Plan & Guidance    │
└──────────────┬────────────┘                     └─────────────┬─────────────┘
               │                                                │
               ▼                                                ▼
[ Access $17 Blueprint ] [ Book $197 Consultation ]If you prefer a self-paced, hands-on approach, our $17 blueprint gives you all the essential guidance and copy-ready assets required to execute statutory disputes independently:
- 35-Page Master Guide: Complete breakdown of FCRA laws, Metro 2 codes, and step-by-step statutory dispute procedures.
- 21+ Copy & Paste Dispute Templates: Ready-to-use letter frameworks—including Section 611 factual disputes, Section 609 MOV demands, CFPB complaint structures, and NOITS drafts—paired with custom AI prompts so you can tailor each letter in seconds.
- Certified Mail & Timeline Guidance: Detailed instructions on how to properly log your mailings and strictly enforce the 30-day investigation window.
If you prefer dedicated support, personalized clarity, and expert guidance through your specific credit report, work directly with our strategy team:
- Complete $17 DIY System Included: You receive the full 35-page guide and all 21+ templates at no extra cost.
- Personalized Credit File Review: We analyze your raw credit reports and collection accounts together to identify every Metro 2 compliance error.
- Custom Step-by-Step Action Plan: Walk away with a clear, tailored roadmap built for your specific financial goals.
- Dedicated Support & Hand-Holding: Navigate complex credit bureau stall letters with experienced, 1-on-1 guidance so you don't have to go at it alone.
Frequently Asked Questions (FAQs)
How long do credit bureaus have to investigate a dispute under Section 611?
Under FCRA Section 611 (15 U.S.C. § 1681i), consumer reporting agencies have 30 calendar days from the date they receive your dispute to complete their investigation. If you send additional documentation during this 30-day window, the law allows an extension of up to 15 additional days (45 days total).
Can I dispute accurate collection accounts?
No. The FCRA protects consumers against inaccurate, incomplete, or unverifiable data. If a collection account is 100% accurate across all Metro 2 fields and fully verified by the furnisher, it may legally remain on your report for up to 7 years. Your focus should be auditing the account for data field contradictions.
What happens if the bureau or collection agency fails to respond in time?
If the credit bureau or collection agency fails to complete the investigation and verify the accuracy of the record within the statutory 30-day window, the item may be eligible for deletion as unverified under 15 U.S.C. § 1681i(a)(5)(A). This is a self-help, DIY educational process.
Credit Bureau Dispute Flowchart Generator
Visualize and document your multi-round FCRA escalation strategy step-by-step. Add each round, track bureau responses, and export your complete dispute timeline.
15 U.S.C. § 1681i(a)(1)
Educational tool only. Not legal advice. © 2026 Everything AI LLC.
Compliance FAQ & Legal Lookup Engine
Instant real-time search across FCRA statutes, Metro 2 fields, e-OSCAR rules, and regulatory escalation guidelines.
e-OSCAR uses Optical Character Recognition (OCR) scanners to parse dispute letters into 2-digit Automated Dispute Verification (ADV/ACDV) codes. Generic internet templates containing phrases like 'Validate this debt' or 'Not mine' trigger e-OSCAR Frivolous Dispute Rejection Codes under FCRA § 612 (15 U.S.C. § 1681i(a)(3)), allowing credit bureaus to dismiss the dispute without contacting the bank.
Legal Disclosures & Operational Compliance
Educational Content Notice: The articles, software tools, digital templates, and blueprints provided on creditrepair.everythingainow.com are published by Everything AI LLC strictly for educational, informational, and self-help purposes. Everything AI LLC, Farkhan Shah, and its affiliates are not a law firm, credit repair organization (CRO) as defined under local or federal statutes, or financial advisory firm, and do not provide formal legal representation, credit repair services, or certified financial planning.
No Guarantee of Results: Individual consumer credit profiles, history, and statutory responses vary. Federal laws such as the Fair Credit Reporting Act (FCRA) (15 U.S.C. § 1681 et seq.) grant consumers the right to dispute inaccurate, incomplete, or unverifiable data directly with Consumer Reporting Agencies (Equifax, Experian, TransUnion). However, no software, template, or guide can guarantee the removal of 100% accurate, timely, and fully verifiable negative tradelines or bankruptcy records prior to their statutory expiration dates.
Credit Repair Organizations Act (CROA) & FTC Compliance: In compliance with FTC regulations and federal consumer protection statutes, we do not charge upfront fees for credit repair performance services, nor do we act as an intermediary to alter your credit file on your behalf. All tools and templates provided are designed to empower you to execute your own lawful, factual disputes directly.
Trademark & Regulatory Attribution: Equifax, Experian, TransUnion, e-OSCAR, CFPB, and FTC are registered trademarks of their respective corporate entities. Everything AI LLC is an independent software and educational publisher and is not officially affiliated with, endorsed by, or sponsored by these agencies. Copyright © 2026 Everything AI LLC. All rights reserved.
Related Articles
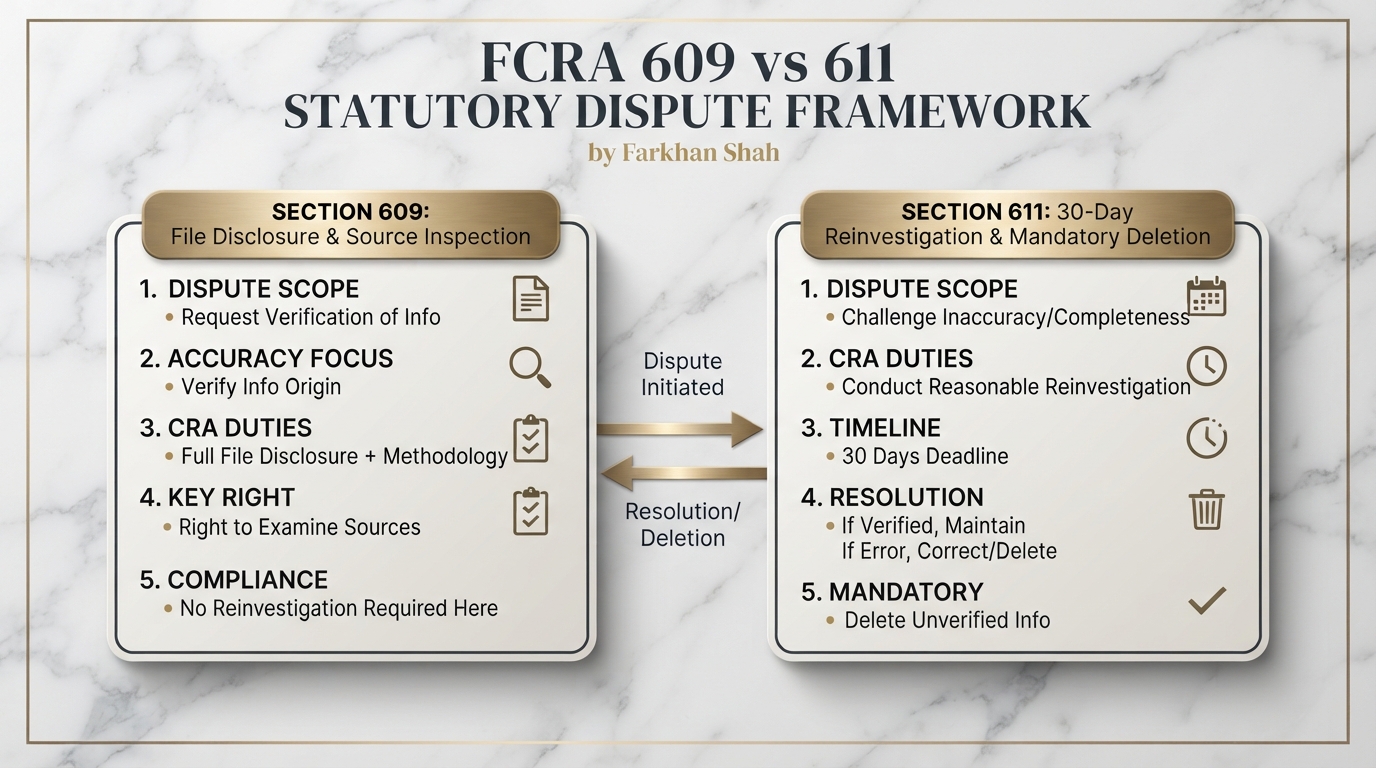
FCRA Section 609 vs 611 Dispute Strategy
Learn how combining Section 609 disclosure rights with Section 611 reinvestigation mandates forces credit bureaus to delete errors.

The Metro 2 Strategy: Why Generic Dispute Letters Fail
Learn why traditional dispute templates trigger automated e-OSCAR frivolous rejections.