If you are preparing to apply for a mortgage (FHA, VA, or Conventional) within the next 30 to 90 days, your credit profile is about to face intense scrutiny. Mortgage underwriters evaluate credit differently than credit card issuers, and a single misplaced remark or algorithm flag can delay your closing. Here is an educational 30-day blueprint to help you understand how FICO 2/4/5 scores work, identify reporting inaccuracies, and prepare your credit file for automated underwriting with confidence.
Executive Summary & The FICO 2/4/5 Reality
The first shock most homebuyers experience is realizing the credit score they see on their banking app is not the score the lender uses. Consumer apps typically display FICO 8 or VantageScore 3.0, which are highly forgiving of older collections and high utilization.
Tri-Merge FICO 2/4/5 Qualifying Calculator
Simulate how mortgage lenders determine your qualifying middle score and detect Desktop Underwriter (DU) hard stops.
Mortgage FICO® 2/4/5 Score Simulator
Estimate how key credit preparation actions (AZEO, dispute remark removal, AU audits) shift your qualifying tri-merge middle score and lower your 30-year interest rate.
1Input Your Current Baseline Mortgage FICO Scores
Classic Mortgage Models2Toggle Credit Preparation Actions to Simulate Improvement
2 Actions ActiveExecute AZEO Method (Revolving Utilization < 1%)
Pay revolving balances down to $0 on all cards except one card reporting 1% balance ($10-$20).
Purge Active Dispute Remarks (Code XB/XC)
Remove dispute tags from open accounts to clear Automated Underwriting System (DU/LPA) hard stops.
Remove High-Balance Authorized User Account
Remove borrower from an AU credit card with high balance that inflates DTI or carries late history.
Clean Up Recent Hard Inquiries (< 120 Days)
Audit permissible purpose for non-extension inquiries or freeze bureaus during pre-approval.
Purge Medical Collections (< $500 or Paid)
Delete paid or under-$500 medical collection accounts under national credit bureau reporting rules.
Tri-Merge Qualifying Middle Score Shift
Estimated 30-year cumulative interest savings: $93,216 on a $380,000 loan.
Mortgage lenders, however, are mandated by Fannie Mae and Freddie Mac to use older, stricter scoring models: Equifax (Beacon 5.0), Experian (Fair Isaac v2), and TransUnion (FICO Risk Score 04)—commonly referred to as FICO 2, 4, and 5. The lender will pull all three and use the middle score for underwriting.
Furthermore, your loan isn't initially approved by a human; it's run through an Automated Underwriting System (AUS) like Fannie Mae's Desktop Underwriter (DU) or Freddie Mac's Loan Product Advisor (LPA). These systems are ruthless when evaluating specific credit data.
1. The "Dispute Remark" Trap & Metro 2 Compliance Codes
Having the phrase "Consumer disputes this account information" on your credit report is a massive red flag during the mortgage process. Under Fannie Mae and Freddie Mac guidelines, Desktop Underwriter (DU) will trigger a hard stop if it detects active disputes on accounts with balances.
Why? Because when an account is in active dispute, the AUS excludes the monthly payment and balance from Debt-to-Income (DTI) calculations, masking the true financial liability of the file. You must resolve or remove these remarks before applying.
[ Active Dispute Remark (Code XB/XC) ] ──► [ AUS Excludes Balance ] ──► [ DTI Masked ] ──► 🚨 HARD STOP ON APPROVALThe Removal Protocol: You may contact the credit bureaus to request removal of dispute remarks. This requires a specific compliance request asking the bureau to remove the XB/XC Metro 2 compliance condition codes. Important: removing a dispute remark from a negative account can cause the account to be re-scored, which may affect your FICO scores if the negative history is factored back in. Consider consulting your loan officer before making this change.
2. Credit Utilization Optimization & The "AZEO" Method (All Zero Except One)
You've likely heard you should keep your credit card utilization under 30%. For mortgage underwriting, 30% is far too high and may negatively impact your qualifying middle score. To optimize your FICO 2/4/5 scores, you may implement the All Zero Except One (AZEO) method.
Here is how it works: Pay down all your revolving credit card accounts to a $0 balance before the statement closing date—except for one major bank credit card. On that single card, leave a tiny balance (around 1% of the limit, or $10-$20) to report to the bureaus.
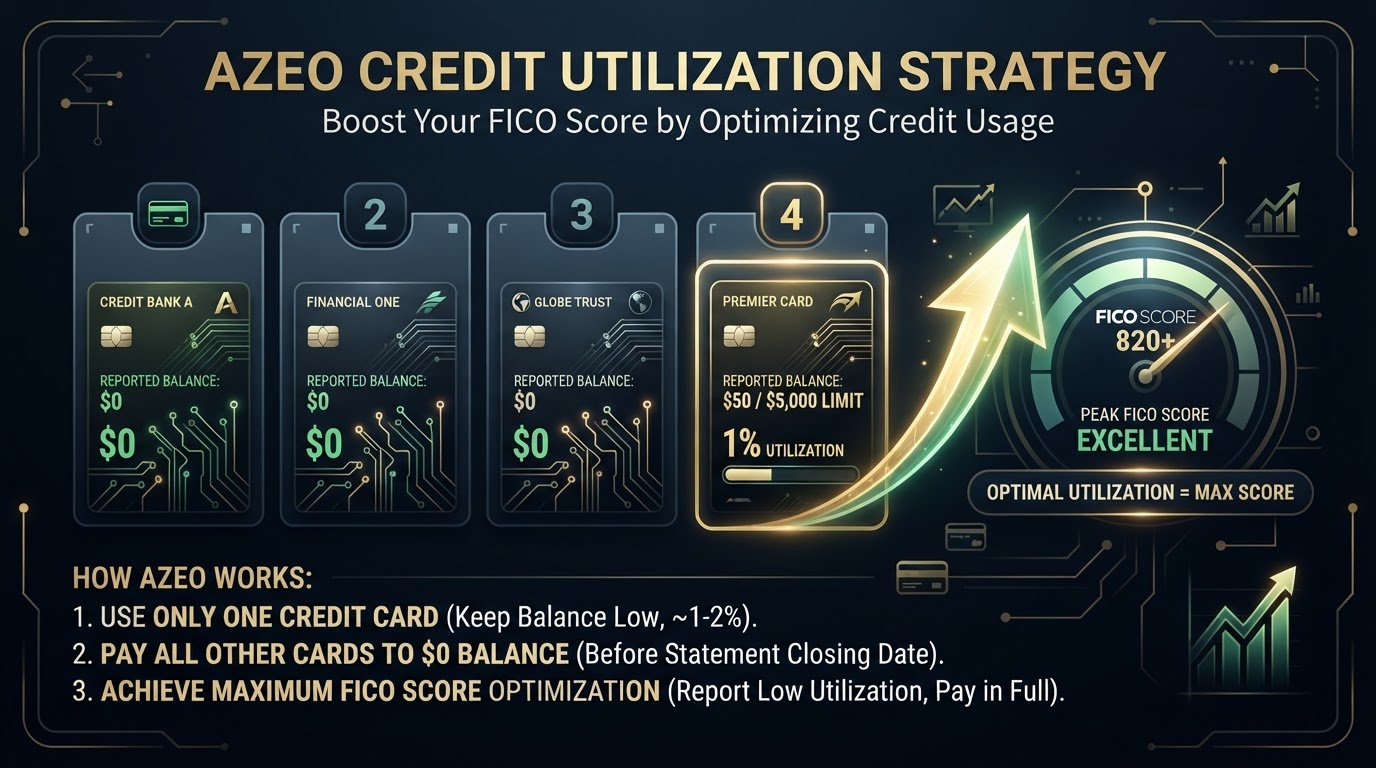
Statement Date vs. Due Date: Creditors report your balance to the credit bureaus on your statement closing date, not your payment due date. You must pay off balances 3 to 5 days before the statement billing cycle closes to ensure a $0 balance is transmitted to the bureaus.
Statement Closing Repayment & Calendar Export Widget
Calculate exact statement paydown amounts and export automatic reminders to your calendar app (Apple, Google, Outlook).
Trying to time your statement closing dates perfectly before applying?
Download our 30-Day Mortgage Credit Prep Checklist for $17 at creditrepair.everythingainow.com
3. Authorized User (AU) Account Audits for Underwriting
Piggybacking on a family member's credit card as an Authorized User (AU) is a common score-boosting tactic. However, mortgage underwriters and AUS algorithms scrutinize AU accounts heavily.
Fannie Mae guidelines require lenders to ensure the primary borrower isn't just artificially inflating their score. If an AU account has a high balance, the underwriter may include that monthly payment in your DTI calculation, which could affect qualification. Conversely, if the primary account holder misses a payment, your FICO 2/4/5 scores may be negatively affected.
Action Item: Review all AU accounts 60 days before applying. If an AU card carries high utilization or late payments, consider removing yourself from the account and submitting a dispute to identify reporting inaccuracies under your FCRA rights.
Mortgage Pre-Approval Credit Audit Summary Sheet
Customize your pre-approval audit metrics below to generate a clean, lender-ready summary sheet confirming your tri-merge score, AZEO status, and dispute remark clearance.
Verify Underwriting Protocol Audit Factors:
================================================================================
MORTGAGE PRE-APPROVAL CREDIT AUDIT SUMMARY SHEET
Prepared for: John Doe
Target Underwriting System: Fannie Mae / Preferred Lender
Qualifying Middle Score Target: 712
Date Generated: August 26, 2026
Authoritative Methodology: Everything AI LLC / Farkhan Shah
================================================================================

1. TRI-MERGE FICO SCORE AUDIT METRICS
--------------------------------------------------------------------------------
- Equifax (Beacon 5.0): 712 Target
- Experian (Fair Isaac v2): 712 Target
- TransUnion (FICO Risk Score 04): 712 Target
- Qualifying Middle Score Status: Pre-Approval Prime Range

2. UNDERWRITING COMPLIANCE CHECKLIST STATUS
--------------------------------------------------------------------------------
[PASS] AZEO Revolving Utilization: All cards $0 except one card at 1% balance
[PASS] Dispute Remarks Purged: Code XB/XC comments removed from active tradelines
[PASS] Authorized User Accounts: Verified low balance and zero delinquent history
[PASS] Credit Bureau Freeze: Bureau freezes placed during 120-day pre-approval window
[PASS] Collection DTI Audit: Non-medical collections < $2,000 threshold or documented
[PASS] Seasoned Reserve Assets: 2 months bank statements free from unverified large deposits
[PASS] Income Verification Packet: W-2s, 1099s, and paystubs aligned with loan application

3. UNDERWRITING DISCLOSURE & ACTION PLAN
--------------------------------------------------------------------------------
This summary sheet confirms that the borrower's tri-merge credit file has been audited according to Fannie Mae Desktop Underwriter (DU) and Freddie Mac Loan Product Advisor (LPA) automated underwriting standards.

================================================================================
Generated via creditrepair.everythingainow.com - Everything AI LLC
================================================================================
Section 4: Prepare Your Credit File for Mortgage Approval
Preparing a credit report for a mortgage application involves establishing a structured, well-documented paper trail rather than relying on guesswork. Having the right educational frameworks in place helps ensure every dispute letter, statement date adjustment, and proof packet is properly organized and aligned with federal standards.
What’s Included in The Weekend Credit Readiness System:
- FICO 2/4/5 Mortgage Optimization Blueprint: Step-by-step guidance on how scoring models evaluate revolving utilization, account age, and tradelines prior to mortgage underwriting.
- Metro 2 & Compliance Code Dispute Templates: 21+ educational dispute templates designed to help you identify reporting inaccuracies, including post-charge-off balances and incorrect compliance codes (including dispute remarks).
- AZEO & Statement Date Optimization Strategy: Clear instructions on timing credit card payments before statement closing dates to lock in optimal utilization ratios.
- DIY Mail & Timeline Tracking System: A structured framework, scheduling roadmap, and tracking method to help you monitor 30-to-45-day bureau investigation deadlines under the FCRA.
- Rapid Rescore & Proof Compilation Checklist: The exact documentation packet checklist (ID proof, dispute receipts, and supporting evidence) required to build a legally enforceable paper trail.
- Plug-and-Play AI Prompt Library: Pre-formatted prompts to feed your specific account facts into AI assistants to personalize every letter in minutes.
Don't leave your mortgage pre-approval to chance or generic online form letters. Download the complete educational system today and take control of understanding your credit file with confidence.
👉 Download The Weekend Credit Readiness System ($17)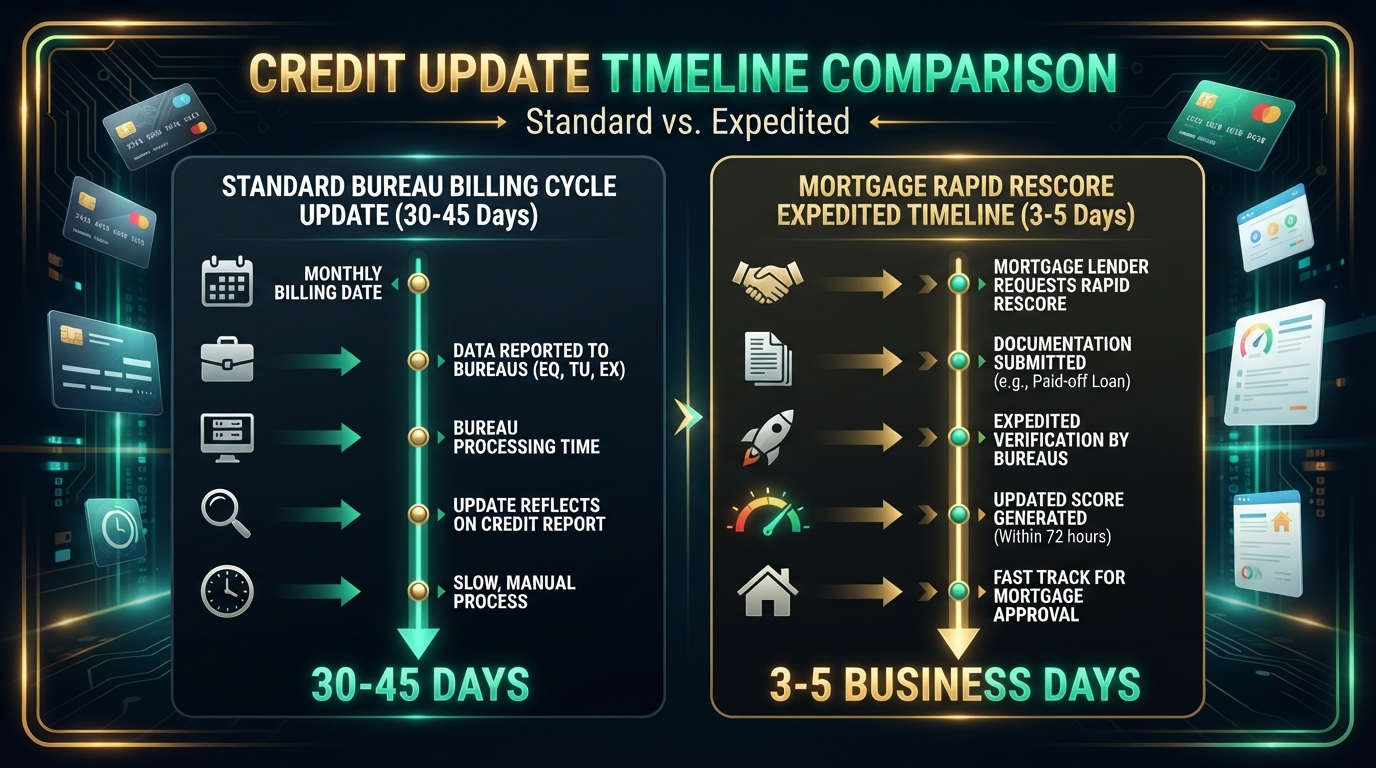
Rapid Rescore Document Package Generator
If you need to update a zero-balance or dispute remark removal in 3 to 5 business days rather than waiting 30-45 days for monthly creditor billing cycles, generate your lender's Rapid Rescore proof packet below.
================================================================================
RAPID RESCORE EXPEDITED DOCUMENTATION SUBMISSION PACKET
To: Credit Bureau Rapid Rescore Desk via First National Mortgage Desk
Borrower Name: John Doe
Account Name: Chase Card Services
Account Number: XXXX-XXXX-1234
Submission Date: August 26, 2026
Target Processing Window: 3 to 5 Business Days
================================================================================

1. EXPEDITED RESCORE REQUEST PURPOSE
--------------------------------------------------------------------------------
This documentation packet is submitted on behalf of the borrower by the mortgage lending institution to execute an expedited Rapid Rescore update across Equifax, Experian, and TransUnion files under Fannie Mae / Freddie Mac guidelines.

REASON FOR RESCORE:
Revolving credit account balance paid in full to $0.00 to optimize FICO 2/4/5 revolving utilization prior to rate lock.

2. ATTACHED SUPPORTING EVIDENCE
--------------------------------------------------------------------------------
[X] Official Creditor Zero-Balance Letter / Payoff Receipt on Chase Card Services Letterhead
[X] Copy of Certified Bank Payment Confirmation or Official Transaction Statement
[X] Signed Borrower Rapid Rescore Authorization Form
[X] Government-Issued Photo Identification & Proof of Address Verification

3. STATUTORY COMPLIANCE & UNDERWRITING NOTICE
--------------------------------------------------------------------------------
Under 15 U.S.C. § 1681i and credit bureau rapid rescore desk protocols, this verified third-party documentation establishes direct proof of account status modification. The credit bureau is requested to manually update the tri-merge file and re-issue updated FICO 2/4/5 scores to First National Mortgage Desk within 3-5 business days.

Submitted by: John Doe
Mortgage Officer Contact: First National Mortgage Desk Rescore Operations Desk
================================================================================
5. The "Hard Inquiry" & New Credit Freeze Protocol
During the 120-day pre-approval window, any new hard inquiry on your credit report will trigger an underwriter request for a signed Letter of Explanation (LOX) confirming whether new credit was extended.
NEW HARD INQUIRY DETECTED ──► UNDERWRITER CLAIMS DTI UNCERTAINTY ──► MANDATORY LOX REQUIREDThe Protocol: Immediately after your mortgage lender pulls your initial tri-merge report, place a Credit Freeze on Equifax, Experian, and TransUnion. This prevents auto-dealers, retail stores, or pre-screened offers from adding unauthorized hard inquiries to your file during escrow.
6. Collections, Charge-offs, and Medical Debt DTI Rules
Not all collection accounts affect mortgage eligibility in the same way. Underwriting engines like Fannie Mae DU and Freddie Mac LPA evaluate collections based on balance thresholds and debt category:
| Collection Category | Underwriting Rule (FHA / Conventional) | Impact on DTI |
|---|---|---|
| Non-Medical Collections > $2,000 Total | FHA requires 5% of the total cumulative balance added to monthly DTI calculations. | Increases DTI artificially |
| Medical Collections | Excluded from mandatory DTI calculation rules under current guidelines. | No direct DTI penalty |
| Paid Medical Debt / < $500 | Removed from credit reports under national bureau reporting guidelines. | Zero score/DTI impact |
Don't Let a Credit Remark Delay Your Home Closing
Get your credit file fully audited and organized before underwriting. Visit creditrepair.everythingainow.com to grab your blueprint or book a 1-on-1 Strategy Session with Everything AI LLC.
Compliance FAQ & Legal Lookup Engine
Search specific statutes, Metro 2 rules, mortgage FICO guidelines, or e-OSCAR rejection codes below.
Compliance FAQ & Legal Lookup Engine
Instant real-time search across FCRA statutes, Metro 2 fields, e-OSCAR rules, and regulatory escalation guidelines.
e-OSCAR uses Optical Character Recognition (OCR) scanners to parse dispute letters into 2-digit Automated Dispute Verification (ADV/ACDV) codes. Generic internet templates containing phrases like 'Validate this debt' or 'Not mine' trigger e-OSCAR Frivolous Dispute Rejection Codes under FCRA § 612 (15 U.S.C. § 1681i(a)(3)), allowing credit bureaus to dismiss the dispute without contacting the bank.
Legal Disclosures & Operational Compliance
Educational Content Notice: The articles, software tools, digital templates, and blueprints provided on creditrepair.everythingainow.com are published by Everything AI LLC strictly for educational, informational, and self-help purposes. Everything AI LLC, Farkhan Shah, and its affiliates are not a law firm, credit repair organization (CRO) as defined under local or federal statutes, or financial advisory firm, and do not provide formal legal representation, credit repair services, or certified financial planning.
No Guarantee of Results: Individual consumer credit profiles, history, and statutory responses vary. Federal laws such as the Fair Credit Reporting Act (FCRA) (15 U.S.C. § 1681 et seq.) grant consumers the right to dispute inaccurate, incomplete, or unverifiable data directly with Consumer Reporting Agencies (Equifax, Experian, TransUnion). However, no software, template, or guide can guarantee the removal of 100% accurate, timely, and fully verifiable negative tradelines or bankruptcy records prior to their statutory expiration dates.
Credit Repair Organizations Act (CROA) & FTC Compliance: In compliance with FTC regulations and federal consumer protection statutes, we do not charge upfront fees for credit repair performance services, nor do we act as an intermediary to alter your credit file on your behalf. All tools and templates provided are designed to empower you to execute your own lawful, factual disputes directly.
Trademark & Regulatory Attribution: Equifax, Experian, TransUnion, e-OSCAR, CFPB, and FTC are registered trademarks of their respective corporate entities. Everything AI LLC is an independent software and educational publisher and is not officially affiliated with, endorsed by, or sponsored by these agencies. Copyright © 2026 Everything AI LLC. All rights reserved.